CFO Message
To Our Shareholders and Investors,
I would like to express my sincere gratitude for your continued and exceptional support.
On the occasion of announcing our financial results for the second quarter (interim period) of the fiscal year ending March 31, 2027, I would like to report on the Group’s financial condition, business progress, the upward revision of our full-year financial forecasts, and the execution status of our "2026–2030 Medium-Term Management Plan."
During this interim period, we achieved revenue growth and a substantial increase in profits across all levels. This performance was driven by the sustained positive impact of price revisions in our sports club operations, the business transfer of eight facilities from Tokyu Sports System Co., Ltd. executed in July, and the expansion of our nursing care and rehabilitation business.
Furthermore, we have revised our full-year consolidated financial forecasts upward to incorporate the performance impact of the business transfer from Tokyu Sports System—which had been under review as of the first quarter—as well as recent business developments. While steadily realizing the fruits of our structural revenue and cost reforms, we will maintain strict financial discipline aimed at continuously enhancing our corporate value.
Current Operating Environment and Outlook for the Second Half
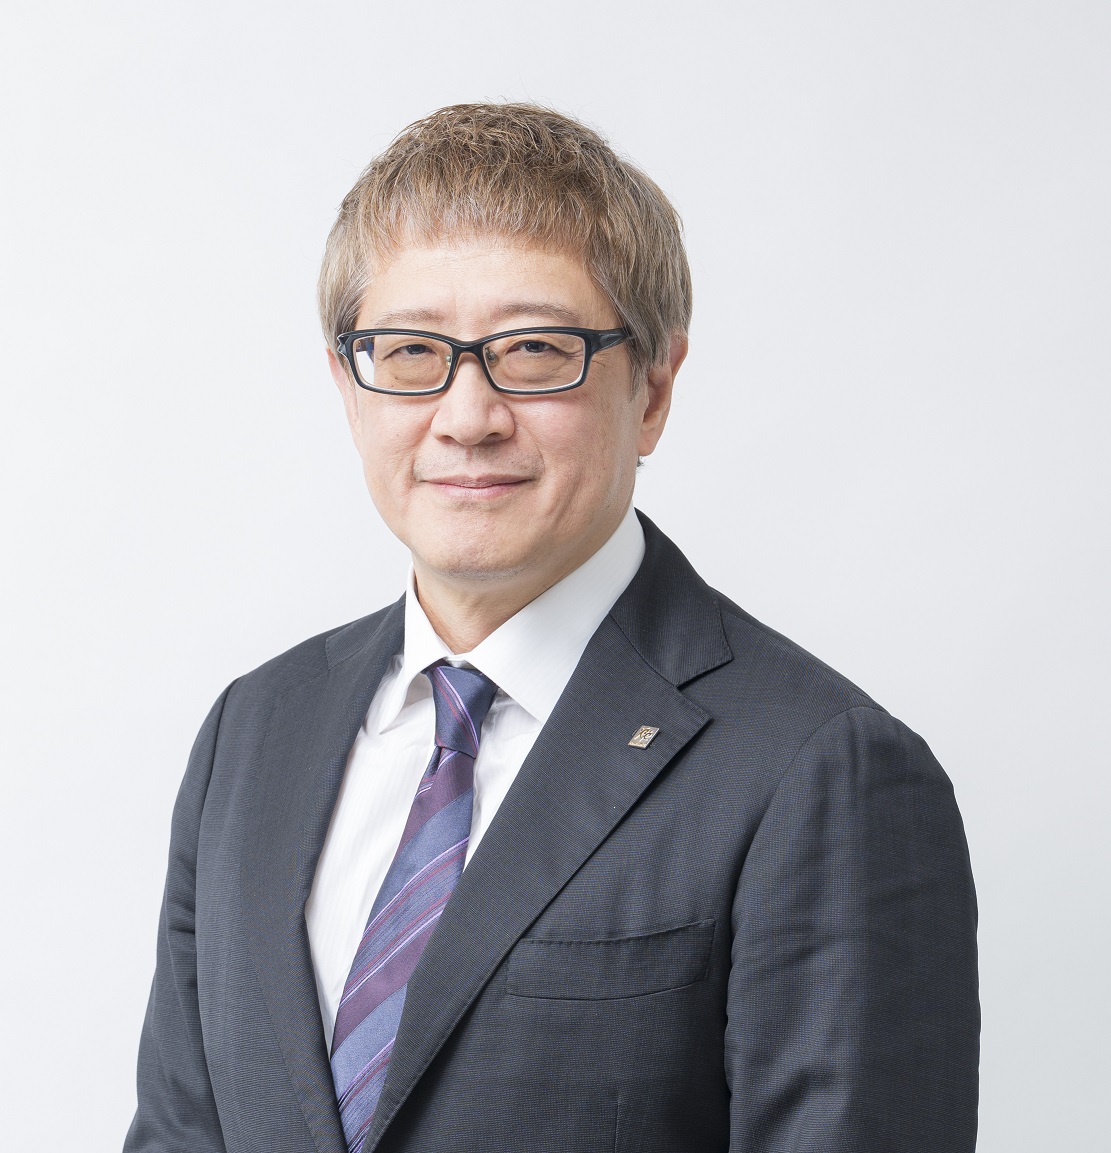
Senior Managing Director, Chief Financial Officer,
General Manager of Management Division
The current operating environment remains uncertain from a cost perspective, characterized by persistent inflation, foreign exchange volatility, and ongoing upward pressure on labor costs. In addition, as an environment with positive interest rates takes root, the importance of managerial decisions focused on securing financial soundness and improving capital efficiency has heightened further.
On the other hand, societal demand for extending healthy life expectancy, preventing frailty, and enhancing individual well-being continues to strengthen. In particular, demand for public-private partnerships (PPP) in regional comprehensive care, municipal health promotion, and school education remains robust, continuously expanding the scope for deploying our Group's integrated solutions. We will appropriately manage cost pressures while transforming the resolution of social challenges into an engine for our sustained growth.
Financial Highlights for 2Q FY2027/3: Progress of Structural Reforms and Performance by Segment
For the interim consolidated accounting period under review, net sales reached ¥33,541 million (up 5.8% year-on-year), operating profit was ¥840 million (an increase of ¥781 million year-on-year), ordinary profit was ¥416 million (an increase of ¥764 million year-on-year), and interim net profit attributable to owners of the parent was ¥176 million (up 618.0% year-on-year). Despite increases in personnel expenses, facility operating costs, and initial expenses associated with the business transfer, comprehensive company-wide cost-control measures proved effective, driving a significant surge in profitability.
Performance by business segment was as follows:
< Sports Clubs and Related Business >
In existing facilities, the price revisions implemented in the previous fiscal year continued to drive higher average revenue per member, contributing to topline growth. Although new membership acquisitions experienced a temporary slowdown due to summer inflation and unseasonable weather, thorough churn-prevention initiatives allowed total enrolled memberships at the end of the interim period to reach 455,914 (up 0.3% year-on-year), maintaining and slightly exceeding the previous year's level.
Regarding store portfolio optimization, while closing three comprehensive facilities in Osaka Prefecture, we successfully launched the eight facilities acquired from Tokyu Sports System in July under the brand names "Renaissance Atrio Due Next" and "Renaissance Atrio Light." Additionally, within the PPP business, we initiated the management and operation of five new facilities, and contracted school swimming lessons expanded considerably, up 25.7% year-on-year.
As a result, net sales amounted to ¥29,957 million (up 5.2% year-on-year), and segment profit reached ¥2,451 million (up 87.3% year-on-year), representing a significant increase in profitability.
< Home Fitness Business >
In e-commerce, sales of our core stepper series remained strong, and the newly launched facial beauty device, "Styly Face Petit," outperformed projections. Conversely, TV shopping sales declined as demand for key legacy products ran its course; however, we are actively rebuilding our earnings base by launching new products such as "Fumicoron," which integrates stepping exercises with EMS technology, and accelerating the renewal of our best-selling lines.
Net sales for this segment totaled ¥1,782 million (down 15.1% year-on-year), with a segment profit of ¥332 million (down 39.8% year-on-year).
< Nursing Care and Rehabilitation Business >
We advanced the rebranding of the five "MyReha" facilities acquired in April into "Genki Gym," focusing on enhancing profitability through higher billing of specialized functional training and oral function improvement incentives. Furthermore, "Kaede no Kaze," acquired as a subsidiary in the previous fiscal year, performed according to plan, and rising utilization rates across both new and existing facilities contributed to overall growth.
As a result, net sales grew substantially to ¥1,801 million (up 59.9% year-on-year), and the segment narrowed its operating loss significantly to ¥11 million (compared to a loss of ¥42 million in the same period of the previous year), marking a material improvement in profitability.
Cash Flow Status and Strengthening the Financial Position
Cash flows from operating activities for the interim period resulted in a net inflow of ¥1,748 million (compared to a net outflow of ¥95 million in the same period of the previous year), demonstrating that our strong cash generation capabilities have been restored alongside improving profitability.
On the other hand, investing cash flows resulted in a net outflow of ¥2,830 million due to the business acquisition, lease deposits and guarantee payments, and capital expenditures. Nevertheless, through agile financing and operating cash generation, cash and cash equivalents at the end of the interim period stood at ¥8,426 million, maintaining sufficient liquidity.
In anticipation of the implementation of the new lease accounting standards, managing interest-bearing debt and reinforcing our financial structure remain paramount medium-term priorities. We will pursue a disciplined balance sheet by rigorously screening investments and shortening payback periods.
Revision of Full-Year Forecasts and Dividend Policy
Taking into account our progress through the interim period and the impact of the business transfer from Tokyu Sports System, we have revised our consolidated full-year financial forecasts upward.
Our full-year outlook now projects net sales of ¥68,500 million (up 5.5% year-on-year), operating profit of ¥2,400 million (up 53.5% year-on-year), ordinary profit of ¥1,500 million (up 89.3% year-on-year), and net profit attributable to owners of the parent of ¥500 million.
Regarding our dividend forecast, we have maintained our projection of an annual dividend of ¥13.00 per common share, comprising an interim dividend of ¥4.00 and a year-end dividend of ¥9.00. Our immediate priority is to rigorously execute Phase 1 of the "2026–2030 Medium-Term Management Plan"—namely, restoring financial health. Once generated cash flows are optimally allocated toward debt reduction and growth investments, we intend to enhance shareholder returns over the long term.
Steadfast Execution of the Medium-Term Management Plan
The new Medium-Term Management Plan, which identifies "structural revenue/cost reform of the sports club business," "accelerated growth of non-club businesses," "headquarters cost containment," and "reinforcement of the financial base" as key strategic pillars, has produced tangible results through the second quarter.
Our initiatives—including the closure of unprofitable locations, the scaling of growth segments such as PPP and nursing care rehabilitation, and structural margin improvements—are progressing steadily.
With respect to strengthening our financial structure, as CFO, I remain acutely focused on generating returns that exceed our cost of capital. I am committed to reinforcing a capital-efficient management framework to achieve our targets of 10% ROE and 6% ROIC.
The Group is dedicated to generating sustainable corporate value as a "Well-Being Co-Creation Company for the Age of 100 Years of Life Era" We sincerely ask our stakeholders for their continued understanding and enduring support.